Brussels – More growth, but only in 2026, and at the same time more debt: Italy is performing poorly. The European Commission’s autumn economic forecasts paint a picture of a country in increasing difficulty. Rising inflation is holding back consumption, investment is falling, and reforms are stalling: against this backdrop, spending is rising, meaning that Italy is set to overtake Greece in terms of public debt as a proportion of Gross Domestic Product already in 2026 rather than in 2027, as previously predicted.
Weak growth and near-bottom ranking in Europe as inflation takes its toll
The Meloni government has been rewarded with an extra half-percentage-point increase in growth for the current year. For 2026, the European Commission forecasts a 1 per cent increase in GDP, whereas as recently as last May it had forecast 0.5 per cent. Italy has therefore performed better than expected due to low inflation, which is now rising again and posing problems for the country’s economy. As a result, for 2027, real GDP growth is forecast at 0.7 per cent, against a more modest expansion in domestic demand. “Household consumption is bound to be constrained by the persistent impact of higher energy prices,” the Commission’s services said.
Despite the half-point increase in growth, Italy’s economic performance remains weak, near the bottom of the ranking. In 2026, Italy is 15th out of 21 countries in terms of growth performance within the eurozone, and 21st out of 27 countries at the EU level. In 2027, it will find itself second from bottom, saved only by France’s slowdown (0.6 per cent), and in 2028, with GDP growth of 0.8 per cent, Italy will avoid coming last solely because of the expected decline in Germany (0.7 per cent).
Rising debt and deficit: the figures don’t add up
The bad news for Italy concerns its debt: by the end of this year, the debt-to-GDP ratio will stand at 137.9 per cent, while Greece’s is forecast to fall to 135.7 per cent. Italy thus officially becomes the EU member state with the highest public debt burden. In 2027, Italy’s debt-to-GDP ratio will rise to 138.8 per cent before falling to 138.2 per cent in 2028, while Greece’s ratio will fall further to reach 126.6 per cent in 2028.
Italy’s deficit is confirmed at 2.9 per cent for 2026. Staying below the 3 per cent threshold laid down in the Treaties would mean being able to attempt to close the excessive deficit procedure opened against the country, which the government has failed to get shelved. Italy will indeed exceed the limit in 2027 (3.5 per cent) and in 2028 (3.2 per cent), but this is due to the exceptional expenditure authorised by the European Commission for governments to invest in defence and tackle high energy costs. It should therefore not be taken into account.
“We could wrap up the process in the spring”, suggests the Commissioner for Economic Affairs, Valdis Dombrovskis. This will happen, however, “if the figures for 2026 are confirmed and if the suspension clause of the internal Stability Pact fully accounts for the deviations for 2027 and 2028”. Meanwhile, he reiterates the agenda, which applies to everyone and even more so to Italy: “We must safeguard our public finances, boost our competitiveness and lay the foundations for stronger long-term growth.”
Taxation, family, work: the reforms called for, albeit diplomatically
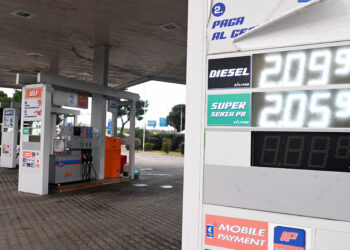
Meanwhile, the Commission has criticised, albeit indirectly, the measures introduced by the government in response to high fuel prices: “temporary cuts in fuel excise duties restrain growth of indirect tax revenues.” A call to change course – and not the only one, as the Commission returns to the issue of the ageing population.
According to the European Commission’s services, “the lagged effects of higher inflation are expected to lift current expenditure, particularly on pensions.” Here too, this is a call for action. It is now up to the government to decide whether to cut pensions or to introduce genuine policies to support the birth rate in Italy.
On the labour market front, Italy is seeing “subdued growth in employment and real wages.” This too was highlighted as an issue requiring action. Still on the subject of the labour market, “self-employment is set to increase, supported by a more favourable tax regime.” Consequently, lower taxes – and therefore reduced revenue for an indebted country – coupled with contracts lacking safeguards, could contribute to the brain drain. For Italy, a reform agenda has been set out tactfully, yet clearly.
English version by the Translation Service of Withub